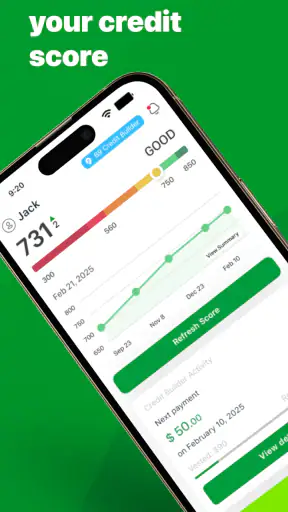
When an unexpected bill arrives before payday, the appeal of B9: Cash Advance is easy to understand. I tried it with that specific problem in mind: not as a replacement for a regular budget, but as a tool for smoothing out a short gap. It is a free finance app from B9 - Get Your Paycheck Early, built around accessing part of your paycheck before the usual payday arrives.
My first impression was that the idea is more useful than exciting. There is no entertainment layer to distract from the purpose. You open it because your timing is awkward, you check what is available, and you decide whether using an advance makes sense. That directness is the app’s strongest first-week quality, but it also raises the most important question: after the urgency disappears, does it deserve a permanent place on your phone?
After spending time with it, my answer is conditional. B9 can be genuinely helpful for someone with reliable income who occasionally needs better timing between paychecks. It is much less convincing for someone who is already using advances to cover ordinary spending every pay cycle. The difference is not a small detail; it determines whether the app acts as a temporary bridge or becomes part of a difficult financial loop.
What the first week feels like
The first week with B9 is shaped by expectation management. The phrase “cash advance” can sound like instant, unrestricted money, but a responsible user should approach it as an early-access tool connected to income rather than as extra income. That mindset changes how I used the app. I looked at the advance as money arriving earlier, not money appearing from nowhere.
The basic appeal is obvious in an everyday situation. Imagine a utility payment is due on Tuesday, while your paycheck normally lands on Friday. If the amount is manageable and your next paycheck can absorb the earlier withdrawal, B9 may help you avoid a late payment or an awkward conversation with a service provider. In that scenario, the app solves a timing problem. It does not solve a budget deficit, and treating it as one would be a mistake.
The app is free to download, carries an Everyone age rating, and works on devices running Android 8.0 or later. That makes it accessible to a broad group of users, although access to a finance service still requires careful attention during setup. I would not rush through identity, income, or account-related screens simply because I was worried about a bill. Financial apps deserve slower reading than social apps.
B9 has built substantial visibility in its category, with over a million installs and a 4.6 average from around eighteen thousand ratings. Those figures suggest that the concept resonates with many people, but they should not replace personal checking. A high average cannot tell me whether the service fits my pay schedule, whether the available amount will suit my need, or whether I will be comfortable with the repayment timing.
One useful first-week habit is to test the app before an emergency. Installing it on the day a payment is due creates pressure, and pressure encourages poor decisions. I would rather explore the interface when my balance is stable, understand the steps involved, and decide in advance what kind of expense would justify an advance. That preparation is more valuable than simply having another finance icon available.
Where the early appeal is strongest
B9 makes the most sense when the expense is both necessary and temporary. A prescription, an important household bill, or a small transport problem can be easier to handle when the paycheck is close but not yet available. The app is also more attractive for people whose employers pay on a predictable schedule and whose regular expenses are already understood.
I would be cautious if the need is vague. “I might spend this later” is not a strong reason to take an advance. A specific bill with a known amount and date gives me a clear repayment plan; a general desire for more spending room does not. This is one of the practical differences between a useful cash-flow tool and an impulse-funding tool.
The developer, B9 - Get Your Paycheck Early, has made the product’s purpose clear, but the user still has to supply the judgment. The app can present an option; it cannot decide whether taking that option will leave enough money for rent, food, transport, or other commitments. I found that the first week was most successful when I treated B9 as a decision checkpoint rather than a button to press automatically.
What remains useful from month to month
The lasting value of B9 depends on whether my financial life contains occasional timing mismatches or a permanent shortage. For the first situation, the app can remain useful over time. If payday consistently arrives after an important direct debit, early access may reduce stress during those recurring moments. The benefit comes from predictability, not novelty.
For monthly use, I would create a simple rule: only request an advance for an expense that is already accounted for in the next paycheck. That rule sounds basic, but it prevents the most common mental error in this category—counting the advance as new money. If I use early access for groceries today, I need to remember that the next paycheck will be smaller in practical terms because part of it has already been used.
This is where B9 differs from a standard budgeting app. A budget app helps me see patterns, assign money, and plan ahead. A bank overdraft may cover a transaction automatically, but it can create its own costs and complications. A credit card offers flexibility, yet it can encourage a balance to roll forward. B9 sits in another part of the decision: it focuses on bringing expected pay forward, which may be cleaner for a short gap but less suitable for an ongoing cash shortage.
I would not use it as my only financial system. I still need a bank account, a way to track upcoming bills, and a small buffer whenever possible. B9 is most valuable when it fits into that structure. Without those supporting habits, the convenience can hide the fact that every advance changes the shape of the following pay period.
One non-obvious advantage of using the app periodically is that it can expose a recurring timing problem. If I repeatedly need money during the same week, that is useful information. The answer might be changing a bill’s due date, moving money into a separate buffer account, adjusting a subscription, or rebuilding the monthly budget. In that sense, B9 can act as a warning light. If I ignore the warning and keep advancing, the app becomes part of the problem.
A realistic recurring scenario
Consider a worker paid every other week whose phone bill and car insurance fall just before payday. In one month, an advance could prevent both payments from colliding with an empty balance. The next month, the same person might use it again, but only after checking that the reduced upcoming paycheck still covers housing, food, and transportation. If the calculation works, B9 provides breathing room. If it does not, repeating the advance simply moves the shortage forward.
That distinction is why I would keep a note outside the app showing the amount taken, the reason, and the expected effect on the next payday. This small workflow is more important than it sounds. It turns an invisible future deduction into a visible commitment. I also prefer to review the note before requesting another advance, because the second request can feel harmless when the first one has faded from memory.
The app’s current version is 3.70.0, so users should keep an eye on the experience after updates rather than assuming that a familiar screen will always behave identically. I do not see version numbers as a reason to update blindly or avoid updates altogether. For a finance app, I would install updates from the official store and read important prompts carefully, especially when they affect account access or transaction details.
Long-term users should also ask whether the app is saving them from a genuine cost or merely making an uncomfortable budget easier to postpone. If it helps avoid a late fee or a failed essential payment, the value can be concrete. If it mainly supports discretionary purchases before income arrives, the lasting value is weak. That is my central month-to-month test.
The maintenance burden is small, but not zero
B9 is not the kind of app that demands constant daily attention. That is good, because a cash-advance service should not become another source of screen time. The maintenance burden comes from financial awareness: checking the next paycheck, remembering what has already been advanced, and making sure an early request does not interfere with necessities.
I would review the app before each planned use, even if the previous experience was smooth. The relevant question is not simply “Can I access money?” but “What will this do to my next pay cycle?” Income can change, bills can arrive early, and an expense that looked manageable last month may be unsafe this month. A familiar interface should never create automatic trust.
There is also a practical account-safety routine worth following. I would use a strong device passcode, avoid handling financial information on an unsecured public connection, and check every confirmation screen before submitting anything. These are not special B9 tricks; they are sensible habits for any app connected to personal finances. The convenience of early pay access is not worth careless account handling.
Another maintenance task is deciding when to stop. Before using B9, I would write down a personal limit based on necessities rather than on the maximum the app might make available. That limit should protect the next paycheck. If taking an advance would leave me choosing between food and another bill, I would skip it and look for a different solution, such as negotiating a due date or contacting the bill provider.
Users often ask whether a free app is automatically free in every practical sense. I would not make that assumption. “Free” describes the app’s listed price, not the broader consequences of borrowing early. Before confirming an advance, I would read the current in-app terms, timing information, and any applicable cost or eligibility details shown there. Those are the screens that matter at the moment of use.
I would also avoid building a routine around the app’s availability. A financial tool should be a backup layer, not the foundation of a budget. If my monthly plan only works when B9 is used, the plan is already too tight. That is a maintenance insight many first-time users miss because the immediate result feels successful.
Where fatigue and friction can appear
The first source of fatigue is repetition. The first advance may feel like a relief, but repeated requests can turn payday into a cycle of catching up. The emotional pattern is easy to recognize: a short-term problem disappears, the next paycheck arrives smaller than expected, and another short-term problem appears. B9 does not create that cycle by itself, but its convenience can make the cycle easier to continue.
The second source is uncertainty around eligibility and timing. A user may have a pressing bill and still need to follow the app’s process before knowing whether the available option fits the need. That is why I would not wait until the final hour. I would plan ahead, leave room for review, and keep an alternative ready. Depending entirely on one app for a time-sensitive payment is poor planning.
The third source is the mental accounting problem. Money received early feels separate from the paycheck that follows, even though it is connected to it. I found that the safest approach was to label the advance immediately in my own notes. “Electric bill,” “transport,” or another precise reason is better than “extra money.” A vague label makes repeated use much easier to justify.
Some users should probably skip B9 altogether. I would not recommend relying on it if income is irregular, if several debts are already consuming each paycheck, or if the intended use is entertainment and impulse shopping. It is also not the right substitute for emergency savings. A savings buffer is slower to build, but it does not reduce a future paycheck when used.
There are cases where another option is better. A budgeting app is preferable when the real issue is poor visibility. A direct conversation with a service provider may be better when a bill’s due date is the problem. A credit union or traditional lender may be more appropriate for a larger, planned expense, provided the borrower compares the full terms carefully. B9 is strongest for a narrow cash-flow gap, not for financing a major purchase or repairing a long-standing deficit.
I also would not choose it simply because it is popular. The app’s 7.4 thousand reviews and broad install base show that many people have engaged with it, but popularity does not remove the need to check personal fit. My income schedule, existing obligations, and ability to absorb an earlier withdrawal matter more than the public numbers.
Three habits that make the service safer to keep
- Match every advance to one named expense. This prevents the available amount from turning into unplanned spending room.
- Check the next paycheck in reduced form. Subtract the early amount mentally before deciding whether the request is affordable.
- Set a stop rule before a crisis. If using B9 twice in a row means basic bills become uncertain, pause and address the underlying budget instead.
These habits are deliberately simple, but they change the role of the app. Without them, B9 can feel like a solution that asks fewer questions than a bank. With them, it becomes a controlled option that I can accept or reject based on the consequences.
My long-term verdict
After the novelty fades, B9 earns space on my phone only for a specific kind of user: someone with dependable pay, a temporary timing mismatch, and enough discipline to treat early access as an advance against the next paycheck. For that person, its value is recurring because the same practical problem can appear again, and the app offers a focused way to handle it.
I would recommend it to a friend who occasionally faces an essential bill just before payday and already knows that the following paycheck can cover the commitment. I would tell that friend to explore it before an emergency, read every current confirmation carefully, and keep a written record of what the advance is for. Those steps preserve the convenience without letting it become invisible debt.
I would not recommend it as a permanent answer to expenses exceeding income. If every pay period requires an advance, the app is no longer smoothing timing; it is masking a structural gap. In that situation, a budget review, bill negotiation, savings plan, or qualified financial counselor is more valuable than another quick request.
The product’s free entry point, Everyone rating, Android compatibility from 8.0 onward, and strong public reception make it easy to consider. Still, the lasting judgment comes from behavior after the first use. Does B9 help me handle an isolated problem and return to normal? Or does it make the next payday harder? My answer to that question matters more than the app’s convenience.
Overall, B9: Cash Advance is a focused finance app with a clear use case and a real limitation: it changes when money arrives, not how much money I ultimately have. I like it as a controlled bridge for necessary expenses, and I would keep it available for that narrow purpose. I would not let it become part of my default spending routine. Its best long-term feature is restraint from the user: used occasionally and deliberately, it can be useful; used automatically, it can turn short-term relief into recurring pressure.


